Articles
November 18, 2026
How Jiko’s Platform Simplifies Investing Cash in Treasury Bills
# Sponsored Content
# Cash Investments
# Technology
CEO Stephane Lintner says Jiko lets corporates own T-bills directly and make payments from one account so treasury teams don’t have to choose between safety, liquidity and yield.
"How do you build a bank that can't fail?" Answering that question lies at the heart of why Jiko CEO Stephane Lintner co-founded a fintech platform backed by its own bank and broker-dealer. That uncommon combination is how Jiko gives corporations investing cash direct ownership of highly liquid, virtually risk-free U.S. Treasury bills—with no exposure to bank balance sheets.
Corporates can also make payments from the same account that holds the T-bills and, thanks to Jiko’s platform, they avoid the burden of calling brokers to trade and reinvest bills constantly. “You want a solution with no trade-off, where you have the ability to pay and at the same time store the pure asset directly with no other exposure, you're invested directly in T-bills in your name,” Mr. Lintner said.
“Jiko means ‘self’ in Japanese. It's all about you and your money,” he added.
The scramble to find liquidity. Mr. Lintner’s path to creating Jiko began in 2008 with the onset of the Great Financial Crisis. Armed with a Ph.D. in applied and computational mathematics from Caltech, he had been pricing exotic derivatives at Goldman Sachs. Then Lehman Brothers collapsed. “I was parachuted into the back office the next day amongst three others,” he said. “They put us in front of the mainframe. I had never seen a mainframe. We were asked to help shore up liquidity.”
The assignment gave him “perfect exposure to what banks look like from the inside when a crisis hits,” he said.
Equally important in Jiko’s origin story is the day in 2012 when Mr. Lintner, then at Goldman, figured out that some French and German banks were financing non-traditional trades for hedge funds, using offshore money deposited by individuals—including his father in France.
“It really upset me to think that people like my father, normal people, think they have their money in the bank. They don't know what it's being used for in reality,” he said. “That, combined with what I saw in 2008, just triggered something.”
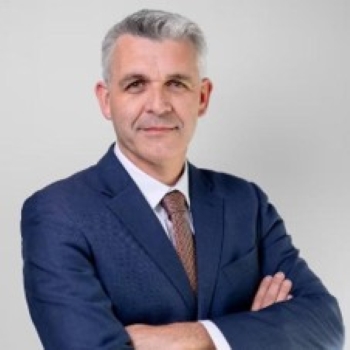
Stephane Lintner, Jiko Co-founder & CEO
How Jiko works. Mr. Lintner decided to leave Goldman and build a bank with no leverage, where every dollar of client money is invested in T-bills and kept off Jiko’s balance sheet. The result is a banking model that offers the functionality of an operating account and, by design, passes the T-bill yield back to the client. To make that possible, Jiko bought a nationally chartered bank, created a registered broker-dealer, and built secure ledger technology on top.
It took several years to achieve the desired outcome: “We're de-levered. We're not running on deposits that we lend out,” Mr. Lintner said. “We just invest everyone's money in real time on their behalf in Treasury bills. We're a platform designed to avoid failure, a high-speed, high-throughput, high-security payment platform where money is natively stored with minimal counterparty risk.” The company has about $3 billion in assets under management and says it has traded $88 billion in T-bills for institutional clients.
The securities—90% of clients hold T-bills of one month duration or less—are held in what is called a “Jiko Pocket.” Mr. Lintner broke down this unique approach for NeuGroup members at a recent Solution Session :
- “It’s a bank account tied to a brokerage account. The bank account processes your payments. It's a zero-balance sweep DDA. So as soon as you have a balance there, we sweep the money through Jiko in real time into the broker-dealer. A U.S. Treasury bill is purchased, and now you hold a T-bill.”
- The process is automated with simple, rules-based software that buys the latest on-the-run T-bill at a set maturity, typically one month, the most liquid point on the curve. “The algorithm is designed to be very simple and understandable,” Mr. Lintner said. Human traders oversee the process.
- “When you use the Pocket like an operating account where you bring money in this week and you bring money in next week, you may have multiple securities because the algorithm will buy the latest on-the-run bill. And so you end up with a few securities in there,” he added. “What you know is they're all less than one month. They're cash equivalents, and when they expire, the algorithm automatically wakes up: ‘So I have cash. I don't want cash. I'm supposed to buy T-bills,’ and just rolls it for you. And you have T-bills again.”
Asked by a NeuGroup member about fees, Mr. Lintner explained, “We're trying to be really tight on the pricing on the bid-ask, and ours is a scale game. We have no balance sheet. We do not lend. I don't have to raise Tier 1 capital as we grow. So it's an AUM game and AUM fees. And of course, if you start transacting with us, there are wire fees that are also very competitive.”
Jiko stores client T-bills in segregated, no-lien accounts primarily at BNY and select custodial partners. Mr. Lintner said in the worst-case scenario—Jiko runs out of cash and has to fold—“the bills are all at BNY; FINRA has access to the records, they'll just call each client, liquidate the bills and send the money. And it's the easiest bank liquidation ever in history because for every dollar that clients have, it's really their T-bill and the securities are there.”
Why Treasury bills, why Jiko? Jiko’s 2026 Corporate Cash Confidence Survey Report , which surveyed close to 200 corporate treasurers and finance leaders, including NeuGroup members, found that 89% of respondents saw value in combining direct T-bill ownership with immediate liquidity for payments. At the Solution Session, Jiko President Eduardo Vergara said that makes perfect sense given T-bills are widely considered among the safest assets offering yield. But he noted that while “T-bills are attractive, they’re burdensome to trade. It’s not simple to manage the rollovers. And they could take time to liquidate.”
Mr. Lintner said most treasury teams don’t buy bills themselves, “but if they do, it’s extremely painful.” The operational burden shows up in the data: Only 14% of respondents to Jiko’s 2025 Corporate Cash Confidence Survey said they purchase T-bills directly through a bank or broker. One Jiko client who holds T-bills at a major bank accepts the pain of spending three hours a month rolling the bills. To compare execution, the client showed Jiko a recent transaction for a one-month bill, saying he knew that the five basis points in spread he paid wasn’t the best price. Jiko discovered the investor had actually purchased a six-month bill with six weeks left and paid a 17-basis-point bid-ask spread.
“So this is the problem with T-bills,” Mr. Lintner said. “They’re securities—you’re exposed to all the usual stuff with calling a broker, getting a quote, you don’t know if it’s good and it takes time. We’ve just made that experience ultra simple and transparent.”
Jiko’s goal is to help corporate treasurers put more idle cash to work. The Jiko survey found nearly half of respondents said that over 10% of their cash is uninvested at any given time, and 23% indicated that a quarter or more remains idle. Said Mr. Lintner, “When we are talking about that 10% sitting uninvested, we can help with automation to bring that down and optimize further.”
Differences with MMFs and bank deposits. Many cash investment managers seeking safety and liquidity stash cash in money market funds (MMFs) that invest in Treasury bills. Many corporates buy funds through portals, a relatively simple process. But Mr. Lintner told members at the Solution Session there is one fundamental difference between the two assets:
“On a T-bill, you know exactly the rate—the rate you quoted me right now is the rate that if you buy the bill today, hold it to maturity, it's a forward rate, you know what you're going to get. On a money market fund, you know what you have today; you don't know what you're going to have tomorrow.” There are other differences as well, he said. “Money market funds, if you read the fine print, typically also have repo. So now you have bank exposure. You didn't ask for that. Liquidity doesn't matter until it matters. And when it matters, it's the only thing that matters.”
That concern is evident in the data. In Jiko’s survey, banking sector stability ranked as the second most influential factor in cash strategy in 2026, and 63% of respondents are concerned that geopolitical tensions could directly affect their cash strategy in the next 12 months.
During the session, one NeuGroup member asked Mr. Lintner why a cash investment manager would onboard Jiko if bank deposits offered similar yields to T-bills. His response: “If you compare it to a bank, you're comparing apples to oranges. A bank may want to try to get your deposits to fund their loan book. You're taking principal risk against the bank. You're not FDIC insured above $250,000.”
He added, “So comparing T-bill rates to bank rates, that's an investment decision where you decide, okay, I'm going to go for the safe asset or fine, I'll lend some money to a G-SIB for all sorts of other reasons, such as revolver lines or supply chain financing; you understand the risk you're taking. In the case of another 2008 or some jitter in the market, that cash may or may not be available.”
The M&A use case. Liquidity always matters to treasury teams that must have it when mergers and acquisitions surface. Jiko says its platform can help make the process smoother, noting the difficulties facing very active acquirers. “When you're buying companies on a day-to-day basis, your treasury function is choking,” Mr. Lintner said. “And that's where the flows are painful: freeing up $10 billion in money market funds, moving it into a bank account so that you're ready to do the wire for the M&A. That starts to be cumbersome, risky, people don't like it, and you lose yield typically.”
Mr. Lintner described a recent M&A transaction where a Jiko client, a public company, had funds sitting in a Jiko Pocket, with yield accruing for a month. At the time of settlement, the buyer issued instructions, and T-bills were sold in real time; wires left Jiko and the seller received the money. “There's no headache, there's no trade-off. It's in T-bills until the transaction occurs,” he said.
If both the buyer and seller have Jiko accounts, the recipient of the cash can immediately purchase T-bills and, Mr. Lintner said, the entire transaction is “risk-free.” He added, “We allow them to hold corporate cash and move it amongst each other. That's what we call JikoNet , which is a product that's now available to corporates. So if you're a large corporation and you're doing M&A and both sides have a Jiko account, you can execute transactions 24/7.” Jiko’s survey shows that 76% of respondents consider 24/7 settlement important, but only 19% can move cash or settle transactions in real time today.
Jiko’s road ahead. Jiko is currently available through Kyriba, a treasury management system (TMS) used by many NeuGroup members. Jiko will soon be accessible to cash investment managers through BlackRock Cachematrix , CashInvest by Morgan Stanley and LINK, State Street’s electronic platform ecosystem which also houses Fund Connect. Jiko plans to secure licenses in the eurozone and Japan to replicate the model with other “risk-free” government assets. The company is also offering its API to fintechs, broker-dealers and other enterprises, so clients can make ultra-short-term T-bill access available under their own brands. Those clients include several large international firms that plan to provide Jiko Pockets to retail customers.
While Mr. Lintner said Jiko doesn’t plan to add other assets such as commercial paper to its Pockets anytime soon, it sees other use cases for corporates using its platform. “If you start opening an account, you're starting to collaborate with us as a partner bank; for large corporations, since we're tech native, we could start streamlining a lot of things for them. So over time, we become a design partner. We start helping with sticky payments, disbursement, organizing cash by purpose through the creation of unlimited Pockets (operating accounts), solving other challenges.”
But Mr. Lintner emphasized that Jiko’s simplicity is its best selling point. “We pride ourselves that our stuff is so elegantly simple,” he said. “Yes, it's just T-bills. But as a result, I can look you in the eyes and say, I know your money's safe with us. I sleep at night and I'm not playing with your money.”
Disclaimers:
Investments in T-bills: Not FDIC Insured - No Bank Guarantee - May Lose Value
All U.S. Treasury investments and investment advisory services provided by Jiko Securities, Inc., a registered broker-dealer, member FINRA and SIPC. Securities in your account are protected up to $500,000. For details, please see www.sipc.org .
Banking services provided by Jiko Bank, a division of Mid-Central National Bank. Commercial and consumer account limitations may vary.
Jiko Group, Inc. and its affiliates do not provide legal, tax, or accounting advice. You should consult your legal and/or tax advisors before making any financial decisions. This material is not intended as a recommendation, offer or solicitation for the purchase or sale of any security or investment strategy. See FINRA BrokerCheck , Jiko US Treasuries Risk Disclosures and Jiko Securities, Inc. Form CRS .
Dive in